
Intro
Raising children involves expenses that can be difficult to predict: food, clothing, childcare, school requirements, transport, activities, and healthcare may all compete for the same household income. Cost saving does not need to mean depriving children or pursuing unrealistic perfection. A sustainable approach protects essentials, reduces avoidable waste, and gives the whole family practical habits that can be maintained during busy or stressful periods.
The most effective strategy is usually a combination of planning, comparison, flexibility, and early communication. Families can reduce pressure by reviewing regular bills, adapting shopping routines, using community resources, and teaching children age-appropriate money skills. Any decision involving nutrition, medicines, treatment, or access to healthcare should preserve safety and be discussed with an appropriate healthcare or social-care professional when needed.
Highlights
A written household budget can reveal recurring costs that are easier to change than major one-off expenses.
Meal planning, reducing food waste, and comparing supermarkets can lower food spending without eliminating nutritional variety.
Second-hand, shared, borrowed, or adjustable items may be practical for rapidly growing children.
Teaching children about money through guidance, pocket money, and controlled spending can build long-term financial skills.
Cost reduction should never delay urgent medical care or compromise essential food, medication, safety equipment, or supervision.
Start with a compassionate family budget
Begin by recording income and essential outgoings for one month, using bank statements, receipts, or a budgeting service. Separate fixed expenses, such as rent or mortgage payments, from variable expenses, such as groceries, transport, activities, and clothing. Include less frequent costs by estimating their yearly total and dividing it by twelve. Birthdays, school trips, uniforms, seasonal heating, and replacement equipment can otherwise appear to be sudden financial emergencies.
Prioritise expenses according to safety, health, housing, nutrition, education, and family stability. Avoid treating every discretionary purchase as a failure; families need rest, enjoyment, and social connection. Instead, identify one or two categories where a small, repeatable change is realistic. For example, reviewing subscriptions, comparing utility tariffs, consolidating errands, or setting a weekly spending limit may be more sustainable than attempting a severe short-term restriction.
Review the budget with any adult who contributes to household decisions. A shared plan reduces misunderstandings and makes it easier to notice financial stress early. If debt repayments, arrears, or an income shock are involved, a free debt-advice or welfare-support service may help identify options before bills become unmanageable.
Reduce food costs without compromising nutrition
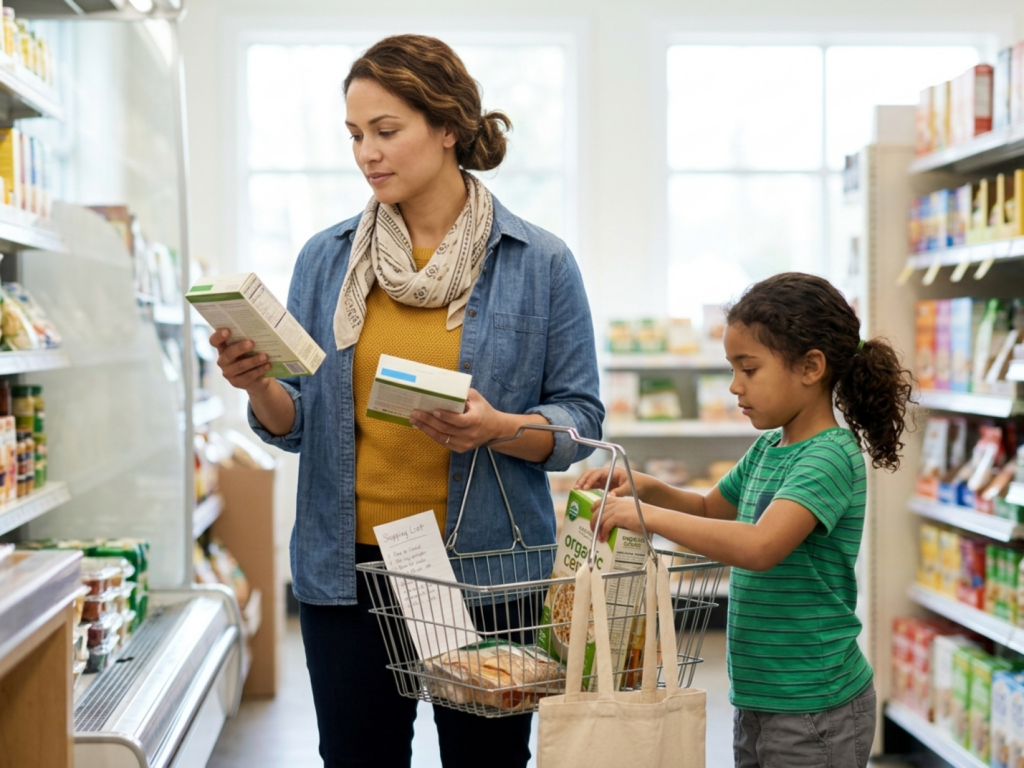
Food is often one of the most adaptable areas of a family budget, but cost saving should not be based on routinely removing nutritious foods that a child needs for growth. Plan several meals around versatile ingredients, check what is already in cupboards and freezers, and write a shopping list. Cooking a larger quantity can provide planned leftovers, provided food is stored and reheated according to local food-safety guidance.
Research involving parents and carers describes practical approaches including shopping at less expensive supermarkets, buying some products in bulk, reducing food waste, and purchasing less fresh food. These choices may lower costs, but they need to be applied thoughtfully. Bulk buying is useful only when the household can safely store the item and use it before it expires. Frozen, tinned, or dried alternatives can be convenient and economical; compare labels, and choose options with less added salt or sugar when suitable.
Keep a small list of low-cost meals that the family accepts, and involve children in selecting fruit, vegetables, or recipes within a defined budget. If a child has an allergy, feeding difficulty, restricted diet, or condition requiring specific nutrition, seek advice from a paediatrician or registered dietitian before making substantial dietary changes. Cost pressures should not lead to unsafe elimination diets or missed meals.
Plan clothing and household purchases
Children may outgrow clothing before it is worn out, so consider second-hand purchases, clothing swaps, resale platforms, library schemes, and hand-me-downs from relatives or trusted friends. Inspect used items for damage, contamination, missing fasteners, and appropriate fit. Some safety-critical products, including car seats, bicycle helmets, and certain sleep products, require particular caution because their history, age, recalls, or structural integrity may be unknown.
Buy around the child’s actual needs rather than an idealised wardrobe. A small number of interchangeable garments can reduce laundry and replacement costs. Adjustable garments, durable fabrics, and school-compliant basics may offer better value over time. Comfort and skin health remain relevant: children with eczema, contact dermatitis, sensory sensitivities, or other skin condition concerns may need specific materials or laundering approaches, so cost should not override clinical advice.
Apply the same principle to toys, books, and equipment. Borrow rarely used items, use public libraries, and check whether local organisations provide equipment exchanges. Before buying, ask whether the item is needed, whether it can be repaired, and whether a safer existing alternative is available. Waiting 24 hours before non-essential purchases can reduce impulse spending without creating conflict around genuine needs.
Use low-cost routines and activities
Many enjoyable childhood experiences do not require expensive admission fees. Parks, local walks, public libraries, community centres, museums with free periods, school-based events, and home-based creative activities can provide variety. Planning one free or low-cost activity in advance may reduce pressure to make an expensive last-minute purchase when children are bored.
Predictability can also help financially. Predictable family routines make it easier to pack snacks, use existing supplies, combine journeys, and avoid convenience purchases. A regular preparation period for school bags, packed lunches, and clothing can reduce forgotten-item costs. A simple visual checklist for children may support independence and reduce repeated reminders, particularly during busy mornings.
For birthdays and holidays, set a total budget before making arrangements. Consider shared celebrations, homemade food, borrowed decorations, or experience-based gifts. Discuss expectations with relatives where possible, especially if multiple households buy for the child. The goal is not to eliminate generosity but to make it intentional and manageable.
Teach children practical money skills
Children can learn financial decision-making through ordinary family choices, adapted to their developmental stage. Explain that a budget is a plan for using limited resources, not a punishment. Younger children might sort needs and wants or compare two prices. Older children can help plan a meal, calculate a total, compare unit prices, or decide how to divide pocket money between spending, saving, and giving.
An academic working paper on teaching children to save describes a combined approach involving pocket money, parental guidance, and controlled spending. In practice, this can mean giving a predictable, age-appropriate amount, agreeing what it is intended to cover, and allowing the child to make limited mistakes without rescuing every purchase. Parents can model delayed gratification by discussing why the family is waiting, comparing alternatives, or saving toward a shared goal.
Avoid using money as the sole measure of achievement or linking basic care to a child’s financial performance. Children should not be made responsible for adult debt, household insecurity, or essential bills. The educational aim is confidence and judgment: understanding choices, recognising advertising pressure, and knowing when to ask a trusted adult for help.
Manage healthcare and education-related costs safely
Healthcare costs can be especially stressful because illness and developmental concerns are difficult to predict. Keep records of appointments, prescriptions, receipts, referrals, and insurance or benefits correspondence where relevant. Ask the healthcare provider, pharmacist, insurer, or local authority whether lower-cost equivalent services, payment support, transport assistance, exemption schemes, or charitable funds are available. Eligibility varies by location, so verify details with the responsible organisation.
Do not ration prescribed medication, split tablets, delay urgent assessment, or substitute a product solely because it is cheaper unless a qualified clinician or pharmacist confirms that the change is appropriate. Families should seek urgent care for serious or rapidly worsening symptoms according to local health guidance. For non-urgent concerns, ask about the most appropriate service and whether a planned appointment, community clinic, or telephone review is suitable.
Education expenses can be reviewed in the same way. Ask schools about uniform exchanges, hardship funds, free meal eligibility, equipment loans, transport support, and payment plans. Communicating early is often more effective than waiting until a missed payment or absent equipment becomes a crisis. For children with additional needs, discuss essential accommodations with the relevant educational and clinical professionals rather than discontinuing support without advice.
Review the plan and protect family wellbeing
A cost-saving plan should be reviewed every few weeks at first, then whenever income, housing, childcare, school arrangements, or health needs change. Track which changes actually reduce spending and which create extra work, conflict, or waste. A strategy that saves a small amount but increases parental exhaustion may not be sustainable. Adjust the plan rather than interpreting difficulty as personal failure.
Financial stress can affect sleep, mood, concentration, relationships, and parenting capacity. Speak privately with a trusted professional if worry is becoming overwhelming, particularly if there is persistent low mood, panic, domestic conflict, or concern about meeting a child’s basic needs. Social prescribing, community support, welfare advice, debt counselling, and primary-care services may provide practical routes forward.
The strongest family approach is usually gradual: protect essentials, make a few visible changes, involve children appropriately, and revisit the plan without shame. Savings do not need to be perfect to be useful. Consistent small decisions can improve predictability while preserving children’s nutrition, safety, healthcare, education, and emotional security.
Important safety points
- Do not delay urgent medical assessment, prescribed treatment, or essential medication to reduce costs.
- Consult a healthcare professional before making major dietary changes for a child with an allergy, chronic illness, feeding difficulty, or growth concern.
- Check the safety and history of second-hand car seats, helmets, sleep products, and other safety-critical equipment.
- Seek early advice if food, housing, heating, supervision, or essential healthcare cannot be reliably provided.
- Do not place responsibility for adult financial problems on a child.
Tools & Assistance
- A monthly household budget with annual costs divided into monthly amounts
- A meal plan, shopping list, and freezer or cupboard inventory
- A price-per-unit comparison when shopping
- A local library, community centre, school, or family support service
- A regulated debt-advice, welfare-rights, or benefits-support service
FAQ
What is the quickest way for parents to identify savings?
Review recent bank statements and receipts, then group spending into essentials, regular commitments, and discretionary purchases. Target one recurring category, such as subscriptions, convenience food, or transport, before making broader changes.
Is buying food in bulk always cheaper?
No. Bulk buying can help when the product is used before expiry and can be stored safely. Compare the unit price and account for waste, storage space, and whether the family will realistically consume it.
How can children learn to save without feeling deprived?
Use age-appropriate pocket money, explain the difference between needs and wants, and allow controlled choices. A small savings goal and parental guidance can teach planning while preserving room for reasonable spending.
How should families reduce medical expenses safely?
Ask clinicians, pharmacists, insurers, or local services about eligible assistance, lower-cost equivalents, and payment support. Never ration medication or delay urgent care without professional guidance.
Where can parents find help when basic costs are unaffordable?
Contact a primary-care or social-care professional, school, local authority, welfare service, food-support organisation, or regulated debt-advice charity. Early contact may identify support before a crisis develops.
Sources
- GOV.UK — Child Poverty Strategy: parents and carers research
- DSE, University of Verona — Teaching Children to Save: What Is the Best Strategy for ...
- StepChange Debt Charity — How do I save money while raising a family?
Disclaimer
This article provides general educational information and is not a substitute for individual medical, nutritional, financial, legal, or social-care advice. Consult an appropriately qualified professional about your child’s specific needs, and seek urgent care for emergencies.





Please log in to leave a comment.